
Meta (formerly Facebook) is implementing significant changes to its advertising policies that will have a direct impact on financial institutions, including credit unions.
These updates center around the introduction of a new Financial Products and Services (FPS) Special Ad Category and stricter restrictions on the use of Customer List Custom Audiences.
Here’s what credit unions need to know to navigate these changes effectively.
Financial Products and Services Special Ad Category
What’s Changing?
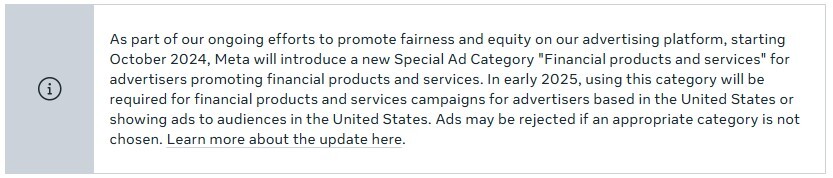
Meta has broadened its former “Credit” category to a more inclusive Financial Products and Services category. This adjustment covers not only credit products like loans and credit cards but also other financial offerings such as checking accounts, savings products, insurance, and payment services.
Implications for Credit Unions:
- Simplified Compliance: Ads for all financial products and services must now fall under this single category, streamlining compliance and ad targeting for financial industries.
- Mandatory by 2025: While existing campaigns under the “Credit” category can continue as is, any new campaigns targeting U.S. audiences must adopt the FPS category starting in early 2025.
Recommended Actions:
- For new campaigns, ensure they are tagged under the updated Financial Products and Services category.
- Monitor Meta’s updates to stay compliant with mandatory changes as they roll out.
Restrictions on Customer List Custom Audiences
The restrictions on Customer Lists is a significant change, and we are in contact with Meta as we try and gain more clarity into this new policy. As we get more information, we will update this post.
What’s Changing?
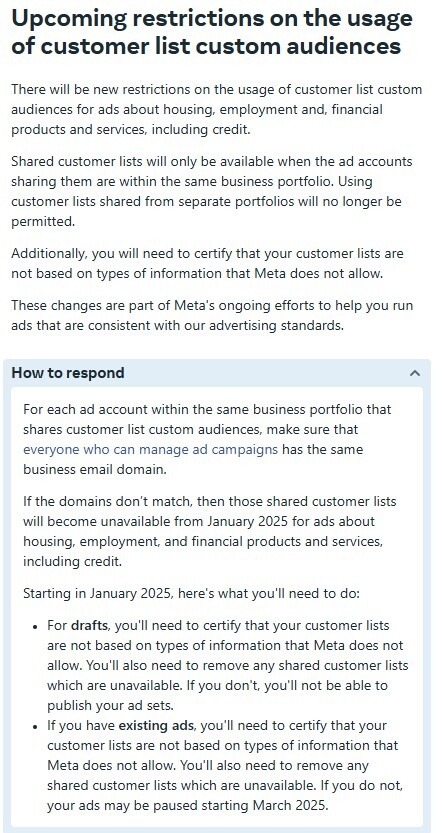
Beginning January 2025, Meta will impose stricter rules on using customer lists for ad targeting. These restrictions specifically affect campaigns under the Housing, Employment, and Financial Products Special Ad Categories (HEC+FPS). This includes the new Financial Products category, along with the “Credit” category many Credit Unions are currently using.
Key updates include:
- Certification Requirements: Advertisers must certify that their customer lists comply with Meta’s policies and legal standards.
- Restricted Sharing: Customer lists can only be shared across ad accounts with the same business portfolio and email domain.
Certification Checklist:
Advertisers must verify that:
- Customer lists are not derived from prohibited or sensitive data sources, such as consumer reporting agencies (CRAs).
- The organization is not classified as a CRA and does not use CRA-sourced data.
- Customer list data will not be used for discriminatory or legally restricted purposes.
Challenges for Credit Unions:
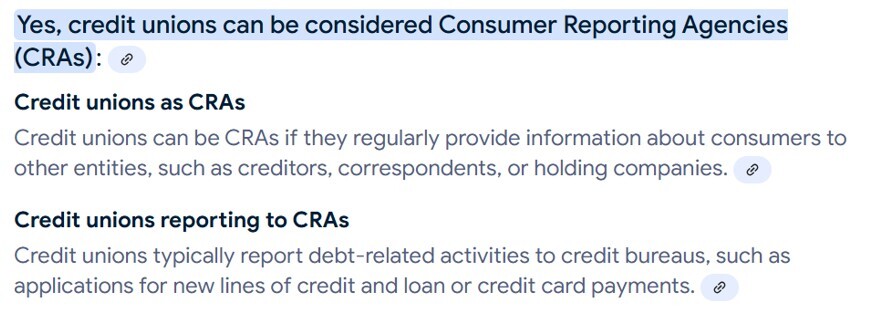
- CRA Classification Ambiguity: The Fair Credit Reporting Act (FCRA) defines CRAs as entities that collect and provide consumer data for decisions about credit, employment, or insurance. Credit unions may face uncertainty about their CRA classification as Meta has not been able to provide us with confirmation on if Credit Unions will be considered as CRAs.
- Administrative Hurdles: All campaign managers must have email addresses with the organization’s domain (e.g., @creditunion.org). This could complicate campaigns managed by external digital marketing agencies.
Action Plan for Credit Unions
To adapt to these changes, credit unions should consider the following steps:
Immediate Actions:
- Audit Customer Lists: Ensure compliance with Meta’s updated certification requirements.
- Clarify CRA Status: Seek legal guidance to confirm whether your credit union qualifies as a CRA under FCRA.
By March 2025:
- Certify existing custom audiences to avoid campaign disruptions.
- Assign domain-specific email addresses to all personnel managing campaigns.
Future Campaign Planning:
- Focus on building compliant remarketing lists from website traffic.
- Evaluate alternative audience targeting methods, and geographic targeting.
Potential Scenarios and Opportunities
Even with restrictions, Meta Ads remains a valuable tool for credit unions. Here are potential scenarios and strategies to maintain campaign effectiveness:
- Scenario 1: Continue using customer email lists to target members broadly or for specific product promotions if compliance is achieved.
- Scenario 2: Shift focus to general member targeting while avoiding product-specific promotions based on past behavior.
- Scenario 3: Rely on remarketing lists from website traffic to target existing members and engage broader local audiences effectively.
Final Thoughts
While Meta’s policy changes introduce new complexities, they also encourage more transparent and compliant advertising practices. Credit unions should prioritize early adaptation, leveraging Meta’s robust advertising platform while exploring alternative strategies to maintain member engagement and growth.
By staying proactive and informed, credit unions can continue to deliver effective campaigns that resonate with their audiences while adhering to evolving standards.
If you have any questions about these new policy changes, or if you would like to discuss how Meta Advertising can be a key component of your digital marketing strategy, please do not hesitate to reach out.
0 Comments